




China’s economic transition: The challenges ahead
November 11, 2026
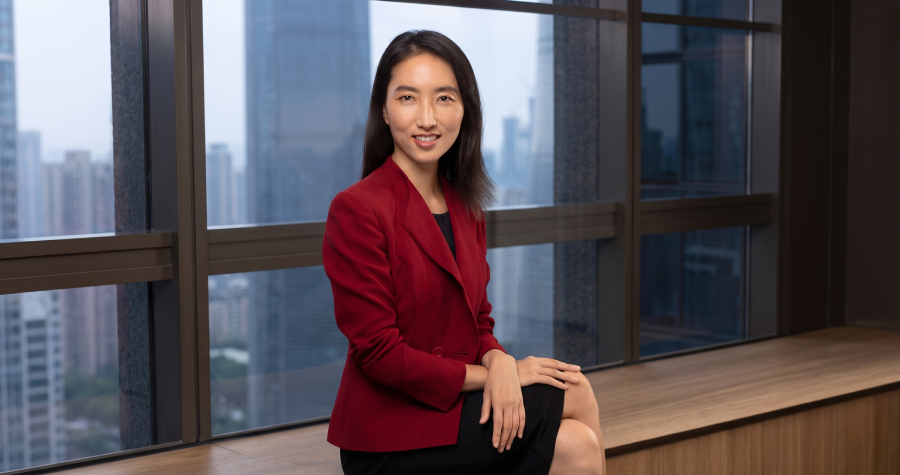
Dr Dan Wang, an analyst at Eurasia Group, discusses China’s prolonged property downturn, the consequences of its industrial ambitions and the challenges facing the economy through 2030
China’s economy is undergoing a structural transformation as Beijing shifts its focus away from property-led growth toward advanced manufacturing, technological innovation and industrial competitiveness. While this strategy has strengthened China’s position in global supply chains, it has also contributed to persistent deflationary pressures, a difficult employment market and growing tensions with trading partners. CKGSB Knowledge spoke with Dr Dan Wang, an analyst at Eurasia Group, about the forces shaping China’s economic transition, the sustainability of its export-led growth and the biggest challenges facing Beijing between now and 2030.
What would you say are the main causes behind China’s persistent weak domestic consumption?
The main reason is still housing. The housing market has been declining for about five years, and we expect it to continue falling for another four or five years before reaching a new equilibrium, with prices returning to around their 2014 levels.
Before the housing downturn, a significant proportion of Chinese consumption was driven by housing-related purchases, including large household items and interior decoration. That part of consumption has largely disappeared. Chinese families typically only purchase these items when buying a new apartment or replacing an existing one.
However, if we exclude housing-related consumption, the remaining consumer basket is actually quite stable. Spending on daily necessities has held up relatively well.
One important point is that, given China’s persistent deflationary environment, the purchasing power of Chinese households is actually increasing. Although higher oil prices have pushed up industrial costs, China’s producer and consumer prices have become largely disconnected. Producers are absorbing much of the increase in costs because competition is so intense.
Most consumer-facing businesses lack the market power to raise prices, which helps explain the persistent deflationary pressure across the economy.
At the same time, falling housing prices have damaged household confidence. For many Chinese families, the decline in the value of their property has created a sense of financial insecurity, even as the prices of everyday goods remain relatively stable.
How can China balance its ambitions for industrial leadership with growing concerns about overcapacity and deflation?
From the perspective of Chinese policymakers, overcapacity and deflation are not necessarily problems to be solved. They are increasingly features of the Chinese economic model.
China believes that, at the right price, it can sell almost anything. Government subsidies are no longer essential for many industrial products because Chinese manufacturers have become extremely cost-efficient.
Decades of investment in infrastructure, machinery and industrial capacity, combined with advances in automation and artificial intelligence, have made the manufacturing system highly efficient. Even without subsidies, China holds a dominant position in many global industries.
At the heart of this economic transition is China’s ambition to double its income by 2035 compared with 2020 levels and become a high-income economy by international standards.
Achieving that objective cannot simply depend on subsidizing consumers. It requires substantial improvements in productivity, and the quickest way to achieve those gains is to double down on high-tech industries.
That is exactly what is happening. The more the government supports advanced manufacturing and technology, the more efficient the industrial system becomes. Supply chains can produce the same goods at increasingly lower costs, which further embeds deflationary pressures in the economy.
For the government and much of the public, low production costs and a relatively low cost of living are not necessarily unwelcome. There is also considerable enthusiasm for advances in AI and automation.
The real concern is employment. China’s industrial transformation is creating significant pressure in the labor market, particularly for university graduates. Many have trained in fields such as business management, finance, education and administration rather than engineering, and their qualifications do not necessarily match the needs of the emerging economy.
This difficult transition could continue for another three to five years before employment prospects begin to improve significantly.
Has China’s economy successfully adjusted to the property downturn, or are the worst consequences still to come?
China has adjusted to the housing downturn relatively well in one important respect: it has not triggered widespread financial stress.
In Western economies, a major property market collapse can often lead to a broader financial crisis. That has not happened in China.
However, the Chinese government is increasingly treating housing as a form of social welfare rather than an engine of economic growth. The priority is affordability, rather than restoring the rapid increases in property prices seen in the past.
As a result, there has not been sufficient intervention to reverse the downward cycle, and I believe the worst of the decline in housing prices is still to come.
I also do not expect China to return to the pre-COVID economic model, when property was a major driver of growth. That era is over, and the economy is being restructured around a different set of priorities.
How has the relationship between the Chinese government and private enterprise changed under Xi Jinping?
Under President Xi Jinping, state-owned enterprises and state-affiliated companies have become more important to the economy because they support China’s broader industrial and global ambitions.
These companies do not operate solely to maximize profits. They are also expected to fulfill social objectives, implement government priorities and undertake overseas investment as part of their responsibilities.
As a result, the relationship between the government and the private sector has become more distant. The two are not as closely aligned as they were in the past.
The government still recognizes private enterprises as an essential part of the economy and relies on them as a major source of innovation.
However, private businesses are increasingly viewed as necessary supporting players rather than the central pillar of China’s economic development strategy.
How sustainable is China’s reliance on exports as trade protectionism increases globally?
I believe China’s exports are highly sustainable, largely because the country is benefiting from at least two major global growth cycles: artificial intelligence and renewable energy.
Chinese producers either dominate key technologies or occupy crucial positions in the upstream and midstream supply chains of these industries.
Global demand in both sectors is expected to continue growing over the coming years, potentially for another decade. That creates sustained demand for Chinese industrial products, many of which are difficult to replace with alternatives from other countries.
The second reason is that China’s exports are increasingly concentrated in industrial inputs rather than finished consumer goods.
Other countries can impose tariffs and trade restrictions on Chinese final products, but they remain heavily dependent on China for the components, materials and intermediate goods needed by their own industries.
That dependence makes it much more difficult to reduce China’s role in global trade, even as protectionist measures increase.
How is China’s growing economic engagement with the Global South reshaping its position in the world economy?
China’s relationship with the Global South has become much closer over the past several years, partly in response to growing resistance to Chinese exports and investment in the United States and Europe.
Chinese companies and policymakers are increasingly focusing on ASEAN countries, the Middle East, Latin America and Africa, particularly resource-rich economies.
China is committing more resources and investment to these markets than before, but that does not mean its expanding presence is free from challenges.
Countries in the Global South also want to develop their own domestic industries and sources of economic growth. They are increasingly demanding technology transfers, greater local content in manufacturing and more employment opportunities for local workers.
These requirements are becoming more important in negotiations with Chinese investors.
I do not think there is a widespread anti-China sentiment across the Global South. However, as China’s economic presence expands, negotiations are becoming more complicated and tensions are also increasing.
Is the expansion of Chinese manufacturing into Southeast Asia reducing dependence on China, or creating a broader China-centered supply chain?
The expansion of Chinese manufacturing into Southeast Asia is actually reinforcing China’s position as the manufacturing center of Asia.
The main reason is the sheer scale of China’s economy and its technological capabilities.
Vietnam, for example, has emerged as a leading manufacturing powerhouse in Southeast Asia. However, its economy is only comparable in size to China’s Yunnan province, and its exports are roughly one-tenth of China’s.
Given this difference in scale, I do not see the relocation of manufacturing capacity to Southeast Asia as a fundamental threat to China’s industrial position.
Chinese companies operating factories overseas also create positive technological spillovers. They transfer expertise and production capabilities to local operations, while sometimes bringing Southeast Asian workers to China for training.
The result is greater regional integration rather than a weakening of China’s manufacturing position.
In this sense, the expansion of production into Southeast Asia is helping to create a more integrated regional manufacturing system in which China remains the central player.
What is the biggest challenge facing China’s economy between now and 2030, and how successfully is Beijing addressing it?
I see two major challenges.
The first is job creation, which is closely connected to social anxiety. One reason involution, or neijuan, has become such a prominent phenomenon in China is that there is an oversupply of labor relative to the number of suitable jobs being created.
China is pursuing a relatively risky strategy by concentrating so heavily on high-tech industries.
This focus is necessary if the country wants to move from middle-income to high-income status. However, during the transition, employment pressures are substantial, and that can generate public dissatisfaction.
I do not expect these pressures to create serious social stability problems. China has an extensive system of social monitoring, while family support networks remain strong. As long as older generations continue receiving their pensions, families can help absorb some of the economic pressure facing younger people.
The second major challenge is political.
China is entering another leadership transition associated with the Communist Party Congress cycle. By the end of 2027, a new group of senior leaders will be in place at both the provincial and central levels.
President Xi is very likely to begin a fourth term, so continuity in economic policymaking should not be a major concern.
However, questions remain about China’s increasingly firm position on territorial disputes, particularly in the South China Sea, and the implications for its relationships with neighboring countries.
China-US relations are relatively stable at present, but the outlook beyond President Donald Trump’s departure from office in 2028 is less certain.
Maintaining stability in that relationship, alongside managing domestic employment pressures and the broader economic transition, will be among China’s most important challenges through 2030.
Bio: Dr Dan Wang is China Director for Eurasia Group, specializing in China's economy and geopolitics. She previously served as the Chief Economist at Hang Seng Bank China based in Shanghai, responsible for macroeconomic forecasting and capital market analysis. Dan holds a PhD in economics from the University of Washington, with expertise in property rights, environmental economics and econometrics. During her postdoc research at the Chinese Academy of Sciences, she designed and led nationwide surveys on agriculture commissioned by the Ministry of Agriculture and the State Council. She is a frequent voice in global media and writes a column for FT China. She regularly delivers keynote speeches at government and industry forums and participates in high-level policy discussions worldwide.
Enjoying what you’re reading?
Article Subscribe (1)
CKGSB Report


Related Articles
Our Programs
Stanford & Silicon Valley Immersion Program
Global Unicorn Program Series
In partnership with Stanford Engineering Center for Global & Online Education
A Silicon Valley immersion for entrepreneurs, intrapreneurs, and investors leading and scaling AI-driven companies.
The program combines academic learning with visits to AI and robotics labs and Silicon Valley companies, giving participants direct exposure to emerging technologies and the businesses developing and applying them.
LocationStanford University Campus, California, United States
Date06 - 11 Dec, 2026
LanguageEnglish with Chinese Translation
Emerging Markets: Innovation and Scaling for Exponential Growth – ASEAN
A China-focused innovation program for ASEAN executives and business owners responding to the impact of AI on their industries.
Gain insights from leading Chese thinkers in Jakarta, with an optional immersion in China and opportunities to connect with the business leaders driving innovation. The program offers a closer look at how developments in China could affect your industry and business.
LocationJakarta, Indonesia
Date23–26 March 2027
LanguageEnglish (with Chinese translation)
Asia Start: AI + Digital Ecosystem China Expedition
An immersive program for entrepreneurs and executives looking to understand China's AI and digital economy firsthand.
Gain the latest trends and insights, strategies, and connections to overcome challenges and support future business growth in Asia and beyond.
LocationChina (Beijing, Shanghai, Hangzhou & optional Shenzhen)
DateApril 19–24, 2027
LanguageEnglish
Intelligent China: AI, EVs & Smart Manufacturing
A three-part program examining China’s advances in AI, electric vehicles, and smart manufacturing.
Through faculty-led sessions, company visits, and exchanges with industry leaders, gain practical insights for your organization's strategy, partnerships, and investment decisions. Join an individual four-day program or complete the full 12-day series.
LocationBeijing, Shenzhen, Shanghai, and Hangzhou
DateSummer – Winter 2027 (three 4-day programs)
LanguageEnglish