




Stop Renting Your Intelligence and Build Your Own
October 19, 2026
CKGSB marketing professor Baohong Sun on why brands that rent AI will never own intelligence.
For two decades, the dominant logic of digital marketing has been about reach: capturing attention, raising conversion rates, chasing traffic efficiency. Baohong Sun thinks that logic is quietly dying. In its place, she argues, a harder and more valuable question is emerging—whether a brand can keep learning, transaction after transaction, until it understands its customers better than any platform does.
Sun, who is Dean’s Distinguished Chair Professor of Marketing at CKGSB, directs the AI × Web3 Research Center. She previously held the Carnegie Bosch Professorship of Marketing at Carnegie Mellon’s Tepper School of Business. Her new book, Brand Intelligence: Navigating the Transformation in the AI and Web3 Era (Springer Nature, 2026), makes a striking argument: marketing should be rebuilt as an intelligent system that learns continuously, adapts on its own, and co-creates value with users.
What makes Sun’s book unusual is that it refuses to treat AI as a set of tools. The distinction Sun draws—between adopting AI and building intelligence—leads to some provocative conclusions: that most companies are using AI to shrink rather than grow, that Chinese and Western AI ecosystems are built in fundamentally different ways, and that within a few years every brand will need a second storefront built not for humans but for the agents that will shop on their behalf. What follows is an edited version of our conversation.
Your book separates “digital-intelligent transformation” from ordinary digital transformation. What is the difference?
AI transformation is about building a closed loop. You keep all your digital assets with yourself, and on top of that you build a system that integrates the user, the data, and the algorithm—so the company understands the customer better and better with each transaction. That’s totally different from digital transformation, and it creates real growth potential.
The key point is that intelligence is not the same as adopting AI. Many companies buy a tool from a third party to reduce workload; that’s just a tool. It becomes intelligent only when you build the closed loop—a system with an objective function, your own data feeding an optimization engine that acts like a commander, and little agents that make everyday decisions and execute them. The system needs arms and legs; it can’t sit in IT. Once the agents execute, they collect the data, feed it back into the pool, and the system learns and improves by itself. It becomes autonomous, not automatic.
You can tell you’ve crossed the threshold this way: you didn’t buy any new tools or make any changes, but your business is growing and your costs are falling. Users come to you day by day, your data warehouse improves every week, and your own algorithm gets sharper, so its decisions become more accurate. The objective function you set at the beginning keeps moving toward optimal. That self-improvement is the sign.
Which companies are actually doing this?
TikTok is almost a native AI company. When a customer comes in, a big agent calls small agents that query the data center for what you watched before, predict what you want now, and optimize your experience; the execution sends you the content, and whether you watch or click away flows back to close the loop. For traditional companies there are four levels: employees using tools themselves; automating one task; building a digital manager responsible for a series of tasks; and finally the AI-native company.
A good example in China is KFC. Over 10 years they built a digital transformation—590 million members, about 90 percent of orders placed digitally through channels they control, so the behavioral data is theirs. It’s a fried chicken company, imagine that. Now each store manager wears an earpiece, and behind it a little agent optimizes staff scheduling and flags low inventory—the AI directing, using the human manager’s mouth to act.
You argue that what’s scarce isn’t technology investment but the organizational design to turn data into learning. Where does that failure usually happen?
The first problem, especially for platform-dependent companies, is that they don’t have enough valuable data to feed the tools. The tools are simple; what you feed them is critical. These companies are so far from their consumers that they have no arm to implement AI—they may have a brain, but without the arm you can’t close the loop. That’s why half my book is about building close connections with the consumer. Every touchpoint is where AI actually gets deployed; it isn’t on your computer, it’s on a product, on an e-commerce site. The more touchpoints you own, the more you can run your AI.
The second problem is organization structure. Today marketing is campaign-specific: I run an ad, I run a promotion. In the AI future that’s wrong—marketing should be customer-based, so when a particular customer logs in, I call multiple agents to serve that one person. The third problem is borrow versus build. If you borrow, you usually lose your data and even your algorithm; a third party that develops your algorithm builds its own closed loop, and you’re left holding only a tool. One thing I want to stress: when I talk about AI, I don’t want companies to fire managers. I want them to explore new opportunities so they can hire more people.
One of your sharpest points is that marketing is shifting from influencing people’s choices to coordinating decisions with agents. How does a brand make itself preferred to another company’s AI agent—and doesn’t that just create a new set of gatekeepers?
Three terms are worth separating. SEO helps humans search. GEO, generative engine optimization, is where an AI helps you search—but it’s still you searching. My work focuses on the third case: a customer sends an intelligent agent that understands her objective, personality, and preferences, and that agent knocks on the brand’s door. To be chosen there, a brand has to satisfy three criteria. First, be discovered—redo your content for machines, not humans: objective, machine-readable, no emotional advertising, which is useless to an agent. Second, be trusted, the layer most people ignore—invest in third-party endorsement and publish your full record: units sold, what customers said, returns, satisfaction scores. Third, be chosen—your product description has to match the agent’s objective function. If the customer wants a comfortable shoe, your description has to meet that.
So brands will need a second interface I call AX—an agent interface, as opposed to UX. You’ll have two storefronts, one for humans and one for agents, and eventually your own agent will negotiate on price with the customer’s agent while she’s asleep. That’s why I tell Chinese companies expanding overseas: if your advertising budget is a million, spend half on humans and half on agents.
You frame Web3 and tokenization as turning users into stakeholders, but consumer adoption has been uneven and dogged by speculation. What separates durable value from hype?
The skepticism is earned. Web3’s first mass application was financial speculation, and a great many token projects were exactly what their critics said they were. I have published on how they come apart: my case study on STEPN, the move-to-earn app, traces how a project that reached millions of users unwound once the reason to join was the token rather than the product. Any brand considering this should read the failure mechanics before the success stories.
Two things survive the speculation. The first is data ownership: the record of what a person does belongs to that person, and the infrastructure now exists to hold it that way. The second is that a brand can hold a direct relationship with its customer without a platform in the middle, and can give that customer a real stake, someone who participates in building the brand and shares in what gets built. A buyer becomes a partner. Neither of those depends on a token price going up, which is why I think they last.
That is also where Web3 and AI meet. Decentralization is not only something that happens to platforms. Brands can decentralize, and so can individuals: with data, cheap infrastructure and a payment layer, one creator can run what used to require a corporation. AI gives them the capability; Web3 lets them own the result.
You describe China as one of the world’s most active laboratories for digital marketing. What do Western executives most misread—and what doesn’t travel?
In China, innovation is pioneered by the platforms, not the brands—the reverse of the US. Western executives underestimate how fast Chinese platforms apply new technology to everyday behavior, and how sophisticated they are at monetizing user data and algorithms rather than just products. Content and commerce merge into one system, and every platform tries to cover all five stages of the decision journey, from discovery to sharing. Fulfillment is extraordinary too—you often receive a product within hours, though it’s very labor-intensive.
The structural difference I’m now studying is this. In the US, the AI landscape is horizontal: each layer—large language models, agent coordination, small models, the interface like Shopify—is built by a different company. In China the same company builds all the layers vertically; Alibaba, Tencent, and TikTok each own the whole stack. My preliminary view is that the Chinese system is good for applying AI to commerce, but the US system is better for motivating innovation and for brands in the long run—though US brands then have to coordinate across all those layers, while Chinese brands pay heavy rent to each platform. And there’s a lesson brands miss: in the subsidy wars of the past two years, the competition was between platforms, yet a large share of the discount was funded by the merchants selling on them. Regulators eventually intervened. Understand the business logic before you fuel the promotion. Don’t pay for a competition that isn’t yours.
For a mid-sized brand without Nike’s or Xiaomi’s resources, is sovereignty achievable or just an aspiration?
Look at Luckin Coffee. It wouldn’t be big without building its own intelligence system from day one. From the start it made every order digital, so it owns the transaction record and trains its own pricing and recommendation algorithms, even though much of its acquisition runs on WeChat and Alipay rails. It now has thousands more stores in China than Starbucks. If it hadn’t, it would still be a neighborhood coffee shop. It’s a strategic choice. Some brands choose to stay on platforms, the digitally-native category, and that’s legitimate. But many brands in China now say they’ve become white-label producers: they make the product, the platform makes the money, prices fall, and they build no brand equity.
The difference shows up after years. A brand that depends on the platform may sell more but accumulates zero intelligence. A brand that builds its own assets knows its customers better every day, operates more efficiently, and earns higher margins. The private domain isn’t mainly for selling or advertising—it’s for building assets: users, data, and algorithms that make the company smarter. Once you understand your own consumers, you can stop paying the platform for those labels and monetize the data directly.
Your book positions marketing to evolve from a cost center into an engine of growth—a claim CFOs have heard before. What would convince a skeptical board?
My book puts technology inside the landscape of a business model. Look at the past 20 years: platforms have made more money than product companies, and they made it not from products but from users, data, and algorithms. When a company sells a product, that’s one side of the transaction. The other side is the relationship you build, the data you collect, the algorithm you develop—and that side has a price tag on it. Companies used to look only at the product and ignore the assets.
I’m not asking brands to drop products and become platforms. I’m asking them to learn from platforms, because they already have both sides of the same transaction. Get closer to the customer and your pricing power, margins, and brand power all rise. For me, marketing isn’t advertising. It’s everything between a company and its consumer, and that includes profit, because profit comes from the customer. So this isn’t about spending. It’s about growth.
As agentic systems take over more judgment, what remains human—and how should a CMO reskill their team?
Even agentic AI has limits, so you need people on top of it for governance and guardrails. AI can’t choose the objective function—that’s a strategic human decision. It can’t define what the brand stands for or how to build equity. There are decisions consumers refuse to delegate to an agent: buying a house, buying luxury goods, getting married. There’s accountability—an agent can’t be held responsible, so a human must supervise. And there’s boundary-crossing: an agent is trained on past knowledge, so it can’t make the creative leaps, such as a shoemaker using its data to venture into health or insurance. Those moves need a human strategic decision-maker.
Brandnetics™ is your culminating framework. If a CMO could implement one principle starting Monday, which would it be?
I coined the word—and trademarked it—because I want managers to see brand intelligence as a living thing. Picture an octopus: it has a central brain, but each of its eight legs has its own sub-brain and fulfills one task, coordinated by a shared nervous system. On each leg are the suckers, and those are the touchpoints that exchange with the outside world—the consumers, the ocean of new opportunities. The octopus draws its nutrition through them.
The one principle is this: use AI to help the octopus grow, and the growth comes from the suckers drawing nutrition from consumers. Too many managers use AI only to cut costs, because the only data they have is on products, logistics, and workers’ skills. Do that and you stop drawing nutrition from outside—and if you don’t eat, you shrink. You shrink by cutting employees, which is the last thing we want AI to do to society. So Brandnetics is about three things: growth, nutrition, and coordination. Start with growth.
Baohong Sun is Dean's Distinguished Chair Professor of Marketing at Cheung Kong Graduate School of Business, where she directs the AI × Web3 Research Center. Her book Brand Intelligence: Navigating the Transformation in the AI and Web3 Era is published by Springer Nature.
Mukul Pandya was the founding editor-in-chief of Knowledge@Wharton, the online management journal of the Wharton School of the University of Pennsylvania, which he led from 1998 to 2020.
Enjoying what you’re reading?
Article Subscribe (1)
Professor profile
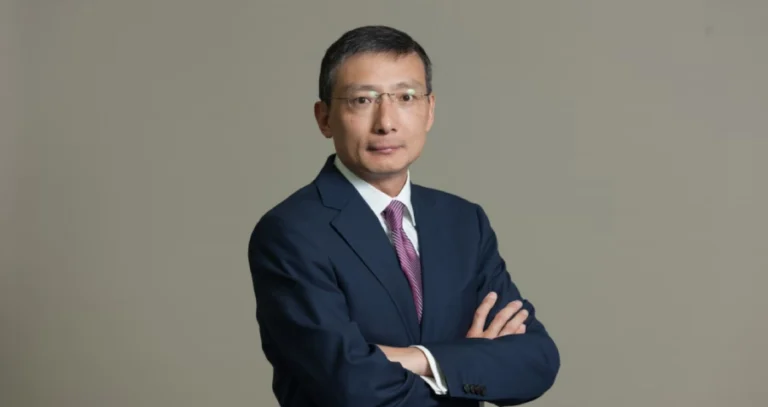
SUN Baohong
Dean's Distinguished Chair Professor of Marketing, Cheung Kong Graduate School of Business (CKGSB)
PhD, University of Southern California


Related Articles
Our Programs
Emerging Tech Management Week: Silicon Valley
Global Unicorn Program Series
In partnership with UC Berkeley College of Engineering
A technology management program for leaders looking to turn emerging technologies into business opportunities.
Combining proven strategies and cutting-edge research, the program helps participants fuel innovation, seize opportunities in emerging technologies, and catalyze transformation within their organizations. Designed for managers, start-up leaders, and technology investors, it includes visits to venture capital firms and technology companies, alongside mentored group projects.
LocationUC Berkeley, California, United States
Date01 - 06 Nov, 2026
LanguageEnglish
Asia Start: AI + Digital China Expedition
An immersive program for entrepreneurs and executives looking to understand China's AI and digital economy firsthand.
Gain the latest trends and insights, strategies, and connections to overcome challenges and support future business growth in Asia and beyond.
LocationChina (Beijing, Shanghai, Hangzhou & optional Shenzhen)
DateNovember 2–7, 2026 | April 19–24, 2027
LanguageEnglish
Intelligent China: AI, EVs & Smart Manufacturing
A three-part program examining China’s advances in AI, electric vehicles, and smart manufacturing.
Through faculty-led sessions, company visits, and exchanges with industry leaders, gain practical insights for your organization's strategy, partnerships, and investment decisions. Join an individual four-day program or complete the full 12-day series.
LocationBeijing, Shenzhen, Shanghai, and Hangzhou
Date December 2026 – July 2027 (three 4-day programs)
LanguageEnglish
Emerging Markets: Innovation and Scaling for Exponential Growth – ASEAN
A China-focused innovation program for ASEAN executives and business owners responding to the impact of AI on their industries.
Gain insights from leading Chese thinkers in Jakarta, with an optional immersion in China and opportunities to connect with the business leaders driving innovation. The program offers a closer look at how developments in China could affect your industry and business.
LocationJakarta, Indonesia
Date2–4 December 2026
LanguageEnglish (with Chinese translation)
Stanford & Silicon Valley Immersion Program
Global Unicorn Program Series
In partnership with Stanford Engineering Center for Global & Online Education
A Silicon Valley immersion for entrepreneurs, intrapreneurs, and investors leading and scaling AI-driven companies.
The program combines academic learning with visits to AI and robotics labs and Silicon Valley companies, giving participants direct exposure to emerging technologies and the businesses developing and applying them.
LocationStanford University Campus, California, United States
Date06 - 11 Dec, 2026
LanguageEnglish with Chinese Translation