



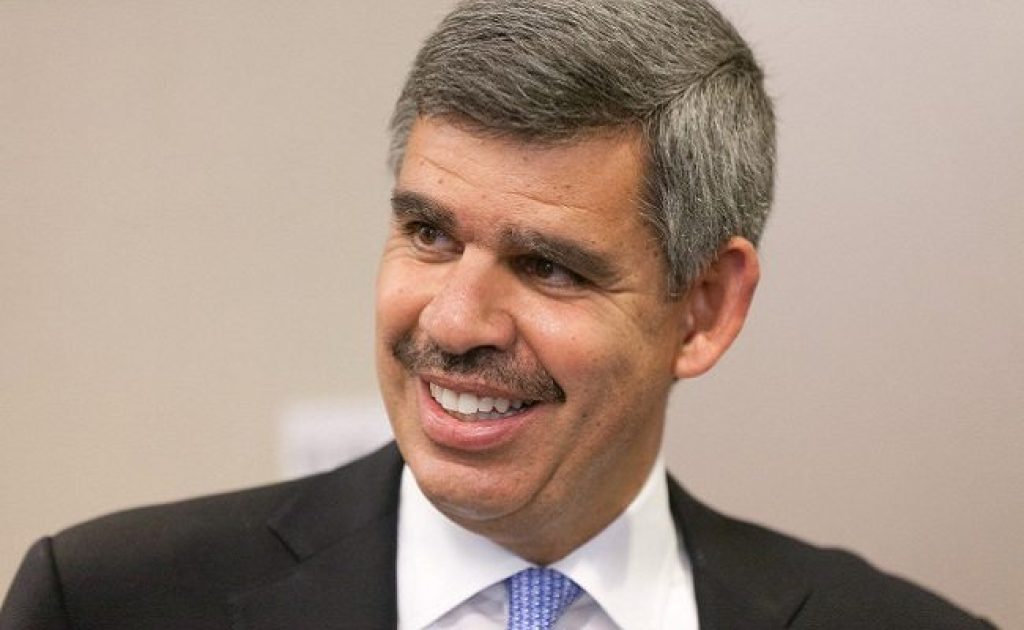

Mohamed El-Erian on Central Bank Effectiveness and China
October 12, 2016
Mohamed El-Erian on why it is important to move away from reliance on central bank-led growth
Central banking is not enough. While monetary policy did much to recover from the global financial crisis, its instruments have been largely exhausted and rendered ineffective. Exceptionally low interest rates and quantitative easing may have kept the engine spinning, but are not pillars of sustainable economic policy.
In China, there might still be scope for more monetary easing, but Mohamed El-Erian warns that, ‘‘China needs to avoid the trap that the advanced countries have fallen into, namely that of excessive prolonged reliance on central banks.’’
El-Erian is chief economic adviser at financial services group Allianz. Formerly at the helm of investment firm PIMCO, he also chairs the Global Development Council of President Barack Obama. In this interview with CKGSB, Mohamed El-Erian explains why it is important to move away from reliance on central bank-led growth and assesses China’s monetary challenges.
Q. Your new book, The Only Game in Town: Central Banks, Instability, and Avoiding the Next Collapse, was recently published in Chinese. A key theme is how central banks have become crucial policy actors. Could you explain why central banks cannot continue this role alone and why it matters to avoid new financial crises?
A. Central banks in advanced economies have seen their contribution to economic policy-making go from important to pivotal. Since the 2008 global financial crisis, and with the exception of a few months, they have been carrying the bulk of the macro-economic policy responsibilities, and have done so for much longer than anyone had anticipated, including the central bankers themselves.
To add to this exceptional phase in the history of central banking, these institutions have also resorted to unconventional measures in an unprecedented way. From negative policy interest rates by the European Central Bank and the Bank of Japan to massive use of theirs — and others’ — balance sheets to purchase securities, it has been a truly remarkable period of experimentation using approaches that were once deemed unlikely if not unthinkable.
Central banks have not been doing this out of choice but, instead, out of perceived necessity. With other policy making entities sidelined by political polarization, central banks have felt compelled to “keep the game going” … to build a bridge to the time when these other actors, with better suited tools for the tasks at hand, will be able to take on their policymaking responsibilities.
But the longer central banks remain as “the only game in town” policy-wise, the lower the benefits and the greater the risk of collateral damage and unintended consequences. And among the things I worry about is the heightened threats of financial instability down the road given how far central banks have decoupled asset prices from underlying corporate and economic fundamentals.
Q. You argue that politicians should take on more responsibility, although the U.S. is lacking bipartisanship. China on the contrary has a single-party state. As such, do you think Chinese politicians are better positioned to play a more active role in shaping resilient policy and hence navigating the various economic challenges?
A. Indeed, and this has played out in more responsive and successful policymaking, and notwithstanding the fact that, from a development economics perspective, China is going through one of trickiest phase – the “middle income transition”—and doing so in the context of international headwinds and isolated pockets of domestic financial excesses.
Q. China’s central bank, the People’s Bank of China, has been propping up its stock markets in a bid to restore confidence in them. In your view, how can confidence be properly restored, as buying frenzies do not change anything fundamentally?
A. One has to be very careful on these issues. The best way to bolster confidence is by sustaining sound economic and financial fundamentals, and doing so in a manner that builds beneficial structural traction and momentum. Other interventions may be warranted in specific cases but they should be approached cautiously; and they certainly should not be relied on. This is particularly the case for both the artificial propping up of markets by public entities and for markets that are being driven by private financial leveraging and engineering.
Q. How do the U.S. Federal Reserve Bank and the People’s Bank of China, differ from each other in terms of influence on the global economy and financial markets?
A. They are both systemically important, that’s for sure as their actions and words have a global impact. But they also differ, particularly when it comes to magnitude. As historically been the case, particularly since the early 1970s and even more so since the early 1980s, the Fed has a larger influence. Indeed, it remains the most powerful of the banks, if only for two reasons. First, it issues the world’s most important reserve currency, the U.S. dollar. Second, U.S. government bonds are very widely held around the world.
Q. Observers are worried about China’s rising debt. How can China avoid a systemic risk to the economy?
A. The best tool is high and inclusive growth, meaning economic growth that creates opportunities for all population segments, while distributing the benefits of said growth evenly across society. There may also be need for some narrowly focused measures to ensure that what are now isolated pockets of over indebtedness do not evolve into something that contaminates general economic activity.
Q. Some economists say that monetary easing in China has been exhausted, and that China is in a liquidity trap. China’s central bank, however, disagrees. Where do you stand?
A. No it is not. China still has scope for further actions. Having said that, the solution is not in the hands of monetary policy. China needs to avoid the trap that the advanced countries have fallen into, namely that of excessive prolonged reliance on central banks. Instead, and as recognized by the Chinese authorities, the country needs to press forward on structural reforms while, as not earlier, also dealing with the isolated pockets of large financial dis-equilibrium.
Enjoying what you’re reading?
Article Subscribe (1)
CKGSB Report


Related Articles
Our Programs
Emerging Tech Management Week: Silicon Valley
Global Unicorn Program Series
In partnership with UC Berkeley College of Engineering
A technology management program for leaders looking to turn emerging technologies into business opportunities.
Combining proven strategies and cutting-edge research, the program helps participants fuel innovation, seize opportunities in emerging technologies, and catalyze transformation within their organizations. Designed for managers, start-up leaders, and technology investors, it includes visits to venture capital firms and technology companies, alongside mentored group projects.
LocationUC Berkeley, California, United States
Date01 - 06 Nov, 2026
LanguageEnglish
Asia Start: AI + Digital China Expedition
An immersive program for entrepreneurs and executives looking to understand China's AI and digital economy firsthand.
Gain the latest trends and insights, strategies, and connections to overcome challenges and support future business growth in Asia and beyond.
LocationChina (Beijing, Shanghai, Hangzhou & optional Shenzhen)
DateNovember 2–7, 2026 | April 19–24, 2027
LanguageEnglish
Intelligent China: AI, EVs & Smart Manufacturing
A three-part program examining China’s advances in AI, electric vehicles, and smart manufacturing.
Through faculty-led sessions, company visits, and exchanges with industry leaders, gain practical insights for your organization's strategy, partnerships, and investment decisions. Join an individual four-day program or complete the full 12-day series.
LocationBeijing, Shenzhen, Shanghai, and Hangzhou
Date December 2026 – July 2027 (three 4-day programs)
LanguageEnglish
Emerging Markets: Innovation and Scaling for Exponential Growth – ASEAN
A China-focused innovation program for ASEAN executives and business owners responding to the impact of AI on their industries.
Gain insights from leading Chese thinkers in Jakarta, with an optional immersion in China and opportunities to connect with the business leaders driving innovation. The program offers a closer look at how developments in China could affect your industry and business.
LocationJakarta, Indonesia
Date2–4 December 2026
LanguageEnglish (with Chinese translation)
Stanford & Silicon Valley Immersion Program
Global Unicorn Program Series
In partnership with Stanford Engineering Center for Global & Online Education
A Silicon Valley immersion for entrepreneurs, intrapreneurs, and investors leading and scaling AI-driven companies.
The program combines academic learning with visits to AI and robotics labs and Silicon Valley companies, giving participants direct exposure to emerging technologies and the businesses developing and applying them.
LocationStanford University Campus, California, United States
Date06 - 11 Dec, 2026
LanguageEnglish with Chinese Translation